A followup on the Leaders Conclave that we held in New Delhi last month. We've been reaching out to both participants and invitees who could not attend. There seems to be interest in pushing forward with the discussion points that the delegates came up with. We're in the process of putting together an event for HR managers in the Indian Oil & Gas sector to action some of these ideas. Stay tuned.
In the meantime, check out the proceedings from the conclave via Slideshare.
Saturday, March 13, 2010


Thursday, February 25, 2010
The Elephant & the Dragon
Over the last decade, the oil consumption needs of India and China have increased exponentially. However demand outstrips supply in both the countries which has led to energy security emerging as a key focus area. In recent months both countries have been outbidding each other to acquire promising oil& gas reserves across borders, across continents.
China has emerged as the clear leader in this race on the strength of its vast capital reserves and availability of cutting edge oilfield services technology. Also at the macroeconomic level the Chinese government has been more aggressive in development of human potential for oil& gas sector as compared to the Indian government. So in this race for energy, how can India Inc. compete with China?
One word- talent.
India’s pool of technically proficient, English speaking engineers have been well utilized in the Business Process Outsourcing and technology offshoring industry. This very pool could be a potent weapon for Indian corporations in the oil & gas space as well. There are a couple of models for this:
• Indian IOCs (a rare bird, India based international oil companies, but I think we’ll start seeing more of these in the coming years) can use in-house talent to help drive and deliver on their international expansions. What would set them apart for other IOCs? Access to cost effective people and processes that they have perfected in their home country. Host countries and governments are looking for knowledge transfer, and this could be a vehicle for that.
• India based services companies can leverage the knowledge base and cost model to compete with other services organization, particularly in SE Asia and the Middle East. Schlumberger has already been sourcing top Indian field engineers for international deployment very effectively over the last decade
• International services companies could build centers of excellence within India. A good model to follow could be IT companies like IBM and Accenture who have built practice hubs in India to support worldwide service delivery. The growth in digitization of services to the energy industry is a trend that can lift a lot of boats in India.
Some forward leaning organizations have already started down this path. If the stars align over the next couple of years in terms of regulatory regimes, hydrocarbon prices and the broad demographic shifts in India, then India Inc. could be a force to reckon with in the global energy industry.
Wednesday, February 17, 2010
Talent landscape in India for Oil & GAs
We have been lax in updating the blog for a couple of months- apologies to our followers. The Global Energy Talent team has been hard at work in expanding the human capability model to different stakeholders- companies, students, academia, regulators. With some wins under our belt, we hope to surface more often and talk about the intersection of the energy industry and human talent.
On this note- Global Energy Talent recently ran a Leaders Conclave in New Delhi on Feb 4, in association with the Petrotech Society of India. CEOs, Directors and chairpersons of different Oil & Gas companies attended, both from India and around the world. The topic of discussion was how to leverage Indian talent for better use in O&G projects in India, as well as around the world. To help set the stage, a question was posed- can India build an O&G industry with the IT industry as a model?
A couple of interesting observations from participants:
- How can the industry better communicate the advantages of a career in O&G to college students.. its still perceived as an old line industry. Can mass media be better used? Who are the influencers that need to be convinced?
- How to best train up young professionals. How can decision making be pushed down lower into the organization so younger execs have ability to take leading decisions earlier in their working careers? What kind of knowledge management practices need to be put in place to ensure organizational knowledge gets passed on?
- What business opportunities open up in the O&G space due to the pool of technical talent in India (which is yet somewhat unpolished). Can Indian-based oil companies use this as a differentiator as they expand to outside geographies? What about remote service delivery using India as center of excellence?
It was a fascinating discussion and we'll be taking these ideas forward in several forums.. stay tuned. If you'd like to receive a precis of the event, do contact us at info@globalenergytalent.com
Wednesday, June 24, 2009
Chinese petroleum producers expanding inorganically
Sinopec today announced a tender offer for Addax Petroleum of Switzerland. Addax management has okayed and recommended the deal to shareholders. Addax has some valuable assets in West Africa and Iraq, both areas where GET has been extending our business, and so of particular interest to us.
Seems like the dragon's expansion is likely to continue, as predicted in a previous post by Ian Rushby. Will there be a nationalist pushback like the Rio Tinto or CNOOC- Unocal deal, or would the invisible hand of the market triumph?
Seems like the dragon's expansion is likely to continue, as predicted in a previous post by Ian Rushby. Will there be a nationalist pushback like the Rio Tinto or CNOOC- Unocal deal, or would the invisible hand of the market triumph?
Thursday, June 18, 2009
GET at Oil & Gas Asia 2009 Exhibition

I just got back from attending the 12th Asian Oil, Gas & Petrochemical Engineering Exhibition in Kuala Lumpur last week. I was present there exhibiting at a booth under the auspices of our partner Max Energy. This post outlines some of my impressions and takeaways from speaking to exhibitors and participants at the show.
- The exhibition was pretty extensive, covering 17000 square feet at the Kuala Lumpur Convention Center. Exhibitors covered two large halls that one often got lost in.
- There were almost 900 participating companies and close to 20000 visitors. It’s billed as Asia’s largest O&G show and it was indeed the case. Looking through the business cards I collected, I seem to have met with people from 17 different countries in the short space of a day and a half. Talk about a globalized industry!
- There seemed to be a much higher degree of optimism in the industry at the event. I was at the OTC show in Houston in May, where I noticed a more subdued mood. I bumped into an exhibitor who had showed at OTC as well, and in comparing notes, he mentioned how he felt that the near term business opportunities seemed more real at this show.
- The economic “green shoots” that analysts have recently been talking about seem to have already sprouted in SE Asia, at least in the O&G space. Well, we’ve also had a 20% runup in oil prices in the last month, which may have contributed to the general sense of new horizons.
- There seemed to be quite a few college students who were checking out the show. I got talking to a couple of these students, and there seemed to be a genuine sense of interest in long term careers in the O&G space.
- Finally, a word about the cuisine. I loved the noodle soups, particularly the kari mee, available at the event concession stands. Messy (still trying to get the curry stains off my favorite tie) but absolutely delish.
Thursday, April 23, 2009
Ghana: A New Growth Area for Oil & Gas
In an earlier post we’ve discussed how Africa is becoming a new frontier for oil and gas exploration for western countries as well as new emerging Asian powerhouses like China and India. We review one country – Ghana which is emerging as an oil and gas exploration hub.
Ghana was the first African nation to have gained independence from British rule. Since its independence in 1957, the country is slowly yet surely moving forward with the help of abundant natural resources especially minerals like gold, diamond, bauxite and manganese. What makes Ghana important to the oil and gas industry is the presence of light oil which was discovered recently in 2007.
As demand for energy has increased in Ghana, many projects relating to the importation of gas via pipeline from nearby Nigeria and Cote d'Ivoire have come up. Although as yet, its upstream oil industry has no crude oil production, Ghana is one of four West African countries with an oil refinery. Oil-derived products supply 70% of Ghana's commercial energy needs and the downstream sector is well structured.
Much of Ghana's emerging oil industry is underpinned by the discovery and early development successes of the “Jubilee field” located in an area straddling the West Cape Three Points and Deepwater Tano contract blocs. The development of the Jubilee field is currently in the first phase, involving the drilling of nine production wells and an additional eight support wells.
Currently, exploration and commercial activity is limited to mid cap players. Texas-based oil exploration company E&P outfit Kosmos is amongst the major players in Ghana’s oil and gas sector, although there have been some reports of Kosmos’ interest in divesting some of its stakes in the country. The other big player is UK based Tullow.
Smaller companies are finding it easier to explore in Ghana than in some of its neighbors in West Africa. This is due in part to advantageous terms of the contract which include factors like no front end payments such as signature or production bonuses; negotiable royalties and income tax; no limit on cost recovery, low rental payments, no restrictions on the repatriation of funds and no import duties on exploration and production equipment and materials.
With such advantages for exploration and development coupled with the quality of light crude, Ghana is poised to be one of the new growth economies in the oil sector.
Tuesday, February 24, 2009
Thirsty Dragon- China’s Energy Security
In little more than a decade China has changed from being a net exporter of oil into the world's second-largest importer, trailing only the United States. Despite the current economic slowdown the country’s oil demand is still forecast to grow by 2.3% this year. With some of the world’s largest and fastest growing cities and an emerging middle-class, demand is coming from both consumer and industrial sectors, including rapidly expanding automobile ownership. This growth in demand cannot be met from domestic production - currently domestic crude oil production supplies only two-thirds of the country’s needs. China’s government estimates that it will need 12 million barrels/day of crude oil by 2020 from the current demand of 7.95 mb/day (IEA).
Securing stable access to oil and gas supplies has become central to China’s economic growth which in turn underpins political stability. So China has been looking outside, in different corners of the world, to find its energy supplies. Until recently the country focused primarily on the Middle East for oil supplies. It was one of the few countries trading with the former regime in Iraq and had large production sharing contracts which were cancelled with the US and allies invasion in 2003. China has also been doing deals in Iran; earlier this year a Chinese state-owned enterprise signed a $2 billion deal to develop the Azadegan field. Nevertheless China recognizes the geopolitical issues and the significance strategically of the Middle East for both the United States and Europe so has set its sights on other areas. China has been prospecting aggressively in the Caspian region and Africa.
Although Africa holds only about 9% of the world’s total proven oil reserves compared to more than 60% in the Middle East, it may hold significant untapped resources. From 2002 to 2003, trade between China and Africa doubled to $18.5 billion; by 2007, it had reached $73 billion – including substantial crude oil imports from Sudan and other African countries. Hydrocarbon rich African countries have decade long relationships with Western oil companies. Wood Mackenzie estimates Chinese companies hold under 2 percent of Africa's known oil reserves – many of these assets were previously held, explored and relinquished by the IOCs. And much of the potential resource growth is in technically challenging deepwater blocks in Angola and Nigeria.
China’s share of Africa’s oil is however growing. Two factors have been driving this. Firstly China’s foreign policy of non-interference in the domestic affairs of its trading partners. Sudan’s government resisted international pressure over its actions in Darfur. How significant was the combination of China’s veto in the UN Security Council and the export of 60% of Sudan’s oil production to China? China also uses aid to provide leverage, supplying easy credit and development knowhow in places as diverse as Gabon and Congo. The Council on Foreign Relations put out a very thoughtful paper last year detailing the growth of Sino-African relations. Oil is the common denominator and China is expected increasingly to use a combination of aid, trade and knowledge transfer to expand its influence in the region and increase its imports. Will the new Obama administration’s clearly stated preferences for reducing its oil import dependency and diversifying to alternative sources of energy give China an opening to construct more deals and expand its presence in Africa in the coming years?
We’ve also recently seen China adopt a model of more direct ownership, fully or partly, of foreign companies. The US congress shot down CNOOC’s attempt to buy into Unocal during the last phase of industry consolidation - but that was in a very different world and has not stopped China’s NOCs from evaluating other options. Will the announcement earlier this month of Chinalco’s proposed massive investment in Rio Tinto be a precursor of similar deals in the oil & gas industry ?

About the author:
Ian Rushby had a 30-year career in BP plc where he held various business leadership, commercial, planning and control positions in BP’s Head Office and Exploration, Finance, Coal and Gas divisions, working in London, the Netherlands, Indonesia, USA and Russia. His most recent assignment was Group General Auditor of BP plc, reporting to the Group Chief Executive, the Board Audit Committee and the Ethics and Environment Assurance Committee. He is also a non-executive Director, Ministry of Defence, UK and Chairman of the Defence Audit Committee.
Friday, February 20, 2009
Biofuels- quo vadis?
There has been a fair amount of hype in the biofuels arena over the last year or two. There were large project announcements on sugar/ corn based ethanol and cellulosic ethanol projects saw more activity beyond the blue print phase. Entrepreneurs also announced a slew of algae based culture for biofuel production. The hype was pretty thick until oil prices slid in late 2008, when a lot of projects started being shelved due to lower oil prices.
So where are we today? Are biofuels programs still going strong? Is the economic platform strong enough to weather the price deflation and volatility of these days? Has the credit crunch affected project financing?
These questions can be answered to a large part by the goverment policies and intervention. Regulatory & energy policies will affect much of the development of this field in the near future. The EU already has a strong set of incentives and program extensions for biofuels development and deployment at the retail end. The US has mandated that by 2022 7% of transportation gasoline come from cellulosic ethanol. The expectation is that the Obama administration will funnel more dollars on R&D in this area. Pure play biofuel companies such as Amyris are already moving along the path to commercialization in anticipation of these incentives.
The market for transportation biofuels is likely to be pretty large. Sandia Labs just released a report this week that found plant and forestry waste and dedicated energy crops could sustainably replace nearly a third of gasoline use in the US by the year 2030.
With those kinds of forecasts, its no wonder there has a steady drip of new venture investments in biofuels. Last year VCs , including a lot of marquee names like Vinod Khosla, funded biofuels startups to the tune of $680 million. Now even the majors are expanding their role. The Wall Street Journal reported yesterday that BP will be developing the world's biggest cellulosic biofuels plant in Florida through its partner Verenium.
The coming months will give a better picture on the investment climate for biofuels projects. The overall trend though is looking positive for the bio fuels industry.
Thursday, February 12, 2009
CERA Week Brief

I’ve been following what’s going on at CERA Week in Houston, albeit remotely. Seems to be some interesting discussions all around. The general effect of the global downturn has been a key topic. BP’s CEO Tony Hayward mirrors our general thinking for the medium term (from the Houston Chronicle)
“I believe this is a crucial moment… The current maelstrom may interrupt but it will not stop the movement of one-third of the world’s population from a rural way of life to an urban one..We are living through a fundamental shift in the balance between supply and demand. This powerful trend will not be stopped by the turmoil we are now experiencing.”
Most of the super majors have not cut capex, even though there have been some announcement of furloughs and headcount reductions.
Will be interesting to see what the participants think of the US stimulus bill and its effect on oil demand.
Tony's pic courtesy of zimbio
Thursday, January 15, 2009
The expat life in China
Despite the global economic slowdown, China continues to grow, although at a slower pace. To maintain the pace of industrialization requires energy, particularly hydrocarbons. China has acquired E&P interests in in regions as varied as Kazakhstan, Russia, Venezuela, Sudan, West Africa, Iran, Saudi Arabia and Canada. Numbers of downstream and upstream facilities are increasing to keep pace with its rising oil consumption, driven both from industrial demand as well as a burgeoning transportation market (The passenger vehicle market is growing at a 7-10% rate over a base of 15 million cars on the road).
As the energy industry booms in China, so is the number of expatriates working in that industry. The country is undergoing high speed modernization and along with it, many cultural changes.
I lived in Southern China for a year as an expat manager at Schlumberger. It was an eye opening experience for me, both professionally and personally. My wife, who had accompanied me, still feels that it was the best foreign posting location for us. The standard of living was particularly high. We also forged some long term & close knit relationships with other expat families there.
However I would urge any expats to venture out of the “expat ghetto” and get to know the real China. Mandarin is the primary language spoken by a vast majority of people in China. The language can be a bit tricky for someone to pick up initially particularly if you’re not used to East Asian languages. Most taxi drivers do not speak or read English. The best solution is to have the address of your destination written in Chinese. I used to carry cards with common words written on it to help me move around the city. It is not that hard to develop workable Mandarin in a couple of months. However, if you are looking for fluency, I recommend attending a language school.
Finding out about expat life in China is easier these days with various online forums and communities. The new visitor can get some valuable tips through these forums. I recommend Dan Washburn’s blog Shanghaiist . Dan’s a freelance writer but has some interesting stories, and slice of life vignettes, and tips for the recently arrived resident in China.
If you are considering taking up projects in China, my advices is set aside all your preconceptions about the country and discover first hand the exciting, wonderful and the sometimes exasperating experience there.
Thursday, January 8, 2009
2008: Looking back
The year 2008 will always be remembered for quite a few things, not least of all for the turmoil in the global economy, particularly in the financial sector where giants like Lehman Brothers, Bear Stearns and others tumbled. The same year also saw the extreme gyrations in the spot oil markets which had far reaching impacts across the world. Today, we look at the top energy stories and related developments during the year that went by – events that will affect many aspects of the year ahead.
Unprecedented crude oil price volatility
During the early part of the year, crude oil rose to its highest ever price of almost $150 per barrel. Peak Oil was almost ready to provide an explanation for it when prices slipped into a four year low of around $30 driven by the economic slump. There are many reasons for this – the demand-supply gap , speculation, political risk, etc. As a consequence, there was a fair amount of economic particularly in transportation- the price of gasoline shot up effecting many consumers.
The price rise also contributed to the poor performance of the airline and automobile sectors. contributing to bankruptcy and consolidation of airlines while the automobile industry faced deep financial trouble when people stopped buying low mileage vehicles.. Later, when the oil price tumbled, some non integrated oil companies were affected adversely, particularly those that made large bets on alternative fuels. The retail side was also impacted, companies such as Flying J declared bankruptcy.
Renewable energy took off, but then didn’t
There was renewed interest and impetus in alternative and renewable sources of energy in 2008. This was one of the direct fallouts of the oil price spike in the middle of 2008. Consumers were increasingly looking for sustainable sources of energy. . The US presidential elections put additional spotlight on this issue and the newly elected president Barak Obama has put a major focus on an attempt to shift away from fossil fuel in the long term.
However the opportunistic investments in alternatives haven’t panned out in the short term. Despite production mandates and federal subsidies, ethanol producers are not minting any money. Falling crude and rising corn prices were deleterious to the effort. Renewable energy enthusiasts hit ground reality when second generation ethanol was delayed. Range Fuels, who intended to start producing by 2008 initially delayed to 2009 and now production isn’t forecast to begin until 2010.
Environment,Nature and Politics
Some major oil refineries had to be shut down because of hurricane Gustav followed by hurricane Ike in North America. Though the outages were short termed, many gas stations in the southeast ran out of gas, raising concerns about starting of something more widespread.
Somali pirates proved to be a major threat to oil vessels operating out of the oil rich African continent. Emboldened by recent ransom payments, they hijacked a Saudi supertanker carrying oil worth $100 million. Countries with interest in the continent have stepped up their maritime security in the area which has considerably brought down the number of such incidents.
Political maneuvering in certain hotspots also created short term demand instabilities. Nigeria, Iran and Venezuela continued to have internal upheavals. The end of the year saw some additional volatility in the Middle East and in gas transport issues between Russia and Ukraine.
Record profits by oil companies
Despite the steep fall in oil prices during the later part of the year, integrated oil companies made record profits with the help of high prices during the beginning of the year. Companies like Exxon Mobil posted biggest profit in history during the same year when downstream profits in refining fell along with gasoline consumption.
OPEC went ahead with its big production cut to counter flagging demands, followed by lowered production in other countries like Russia and Mexico. The results are not visible yet, but many hope this together with a recovering economy will stabilize the oil prices in the near future.
Monday, December 22, 2008
Greener pastures
There are many threads of discussions on clean energy use. The recently concluded US presidential election probably was a catalyst for the uptick in these discussions, particularly in transportation, the area of alternative energy that seems to be most engaging to the average person.. In fact the Go Green” buzzword has gone crossed over from the environmentalists’ domain to the whole world at large. And today industry is responding. The future holds many promises with firms coming up with both fuel-efficient and cleaner options.
Where do we stand right now in terms of live projects of ultra low emission transportation options? Here are some recent advances in the field.
Battery powered cars
In 2008, Tesla Motors began producing the Tesla Roadster – a 100% electric sports car that does 0-60 miles per hour under four seconds a with top speed of around 200 kilometer per hour. That’s pretty fast by any standard, battery or gasoline. The car uses no gasoline and can boast of zero carbon emission (provided the battery is charged from a renewable energy source like solar panels). Single the charge is enough to last for over 350 kilometers. Priced at around $100,000 for two seater, this vehicle has been finding buyers among early adopters.
However, refueling is not as quick as with a vehicle that runs on petrol. It takes about three and a half hours to recharge a fully drained battery. Though it is unlikely to run down a battery before its overnight recharge in urban condition, but it is certainly not practical for long journeys or to places without access to electricity. Another concern is around power supply – if millions of such cars are plugged in, power grids will have to undergo costly grid expansion.
Hydrogen fuel-cell cars
Honda’s FCX Clarity is the world’s first production hydrogen fuel-cell vehicle. The outcome of over two decades of research is a non-polluting sedan (the only emission is water vapour) that can travel up to 450 kilometers on one tank and reach a speed of up to 160 kilometer per hour. The car runs on a lithium battery pack and a hydrogen storage tank. Fuel economy of the Honda FCX Clarity is twice than that of a similar size and performance gasoline powered car.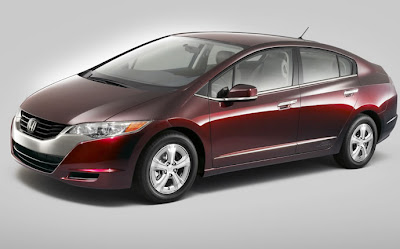
The disadvantage again is the availability of hydrogen filling stations. Even in the US distribution of hydrogen filling station is very sparse. There are just five hydrogen filling stations in the greater LA/Orange County area – where most of the cars are currently leased.
Plane that runs on gas
It is not just automobiles that are turning green. On February 2008, the Airbus A380 became the first commercial aircraft to fly with synthetic liquid fuel processed from gas. The fuel is produced using Fischer-Tropsch process and is known as gas-to-liquids (GTL). The European aircraft manufacturer has admitted it to be a “practical alternative to conventional jet fuel in the short term.”Moreover, GTL enjoys the many other advantages in terms of aircraft fuel burn and virtually free of impurities like sulphur. While the basic science for this has been around for a while, large scale commercial applications are taking off.
I think the next few years are likely to see many more advances such as these.
Where do we stand right now in terms of live projects of ultra low emission transportation options? Here are some recent advances in the field.
Battery powered cars
In 2008, Tesla Motors began producing the Tesla Roadster – a 100% electric sports car that does 0-60 miles per hour under four seconds a with top speed of around 200 kilometer per hour. That’s pretty fast by any standard, battery or gasoline. The car uses no gasoline and can boast of zero carbon emission (provided the battery is charged from a renewable energy source like solar panels). Single the charge is enough to last for over 350 kilometers. Priced at around $100,000 for two seater, this vehicle has been finding buyers among early adopters.

However, refueling is not as quick as with a vehicle that runs on petrol. It takes about three and a half hours to recharge a fully drained battery. Though it is unlikely to run down a battery before its overnight recharge in urban condition, but it is certainly not practical for long journeys or to places without access to electricity. Another concern is around power supply – if millions of such cars are plugged in, power grids will have to undergo costly grid expansion.
Hydrogen fuel-cell cars
Honda’s FCX Clarity is the world’s first production hydrogen fuel-cell vehicle. The outcome of over two decades of research is a non-polluting sedan (the only emission is water vapour) that can travel up to 450 kilometers on one tank and reach a speed of up to 160 kilometer per hour. The car runs on a lithium battery pack and a hydrogen storage tank. Fuel economy of the Honda FCX Clarity is twice than that of a similar size and performance gasoline powered car.

The disadvantage again is the availability of hydrogen filling stations. Even in the US distribution of hydrogen filling station is very sparse. There are just five hydrogen filling stations in the greater LA/Orange County area – where most of the cars are currently leased.
Plane that runs on gas
It is not just automobiles that are turning green. On February 2008, the Airbus A380 became the first commercial aircraft to fly with synthetic liquid fuel processed from gas. The fuel is produced using Fischer-Tropsch process and is known as gas-to-liquids (GTL). The European aircraft manufacturer has admitted it to be a “practical alternative to conventional jet fuel in the short term.”Moreover, GTL enjoys the many other advantages in terms of aircraft fuel burn and virtually free of impurities like sulphur. While the basic science for this has been around for a while, large scale commercial applications are taking off.
I think the next few years are likely to see many more advances such as these.
Friday, December 12, 2008
Think global, hire local
The Oil Boom of the 70’s saw a flurry of oil and gas exploration and production activity in the Middle East. Since there was a dearth of skilled manpower to sustain the fast growth in the region, international and national oil companies turned to experienced staff from overseas to make up for the talent shortage in the region. After 40 years of operation, the situation hasn’t changed much. Though there has been massive growth in the work force, the percentage of expatriates remains the same.
All was okay until recently. There has been an increase in violence directed at expatriates in Saudi Arabia. Meanwhile local unemployment has been growing; Arthur Little’s report released this week highlights how this problem has been growing in the region. Yemen’s unemployment rate is 36%, Saudi Arabia’s is creeping up to 14%.
Finally the cost of expats, typically 2-5 times higher than locals, is also more difficult for NOCs to bear. With the populace seeking to “share the wealth” (eg, the agitations in the Niger delta) governments are interested in greater knowledge transfer, upskilling and general hiring of local talent. The Dept. of Petroleum Resources, Nigeria has recently issued a directive to oil and gas companies to hire local talents instead of expatriates. Similar guidelines are already being provided by licensing and governing bodies in growth regions such as Libya and Iraq.
Instead of viewing such directives as a handicap, International oil companies should make most of the situation to cement their relationships with national governing bodies, while NOCs can build up their image as national champions; giving practical solutions for their country’s expatriates dependence in the future. National oil companies’ aspiration to play a major role in the international energy market is very closely related to building local capability. As they venture into other countries, they will need the expertise to manage their growing international operations.
There is a financial imperative to this calculus too. Block awards and renewals are increasingly tied contractually to local workforce development. IOCs also worry about the approximate 50% of the current expatriate workforce that will retire by the next decade. There is no time like now to build a local workforce that will not only deliver the project at hand but may also be a springboard for regional expansion.
Thursday, December 4, 2008
Oil & Gas hiring amidst Global Recession
Now that the global recession has become a household term and lay offs & pink slips have become a part of our daily vocabulary, you might find it odd to find large number of ads by oil & gas companies on job classifieds. Oil prices are less than half of what it used to be a few months back. So, why are the oil companies still hiring?
Sure, the worldwide economic growth is slowing and the low crude oil price IS affecting new projects. Prospects aren't too bright for any job, be it in Oil & Gas or any other sector. But if you work in the field, there are still plenty of interesting positions. Companies that have started new upstream activities will continue with their effort. Recession or not, that is still a lot of work waiting for workers to complete. In recent report on The Daily Times, a few local oil companies have stopped their hiring, larger companies continue to hire.
There are two major reasons behind it.
First reason is the basic economic principle of demand and supply. Demand for oil and gas remains high due to the emergence of new economies like China and India. Though China has come down from a blistering two digit growth, the current growth rate is at an enviable 9%. India too is not far behind. Even if oil demands slack from traditional giants America and Europe, new economies will continue to drive up the demand. Recently, the International Energy Agency predicts that China and India will need 300% more crude oil for their economies by 2030. This is good enough reason for oil companies to continue investing in exploration & production projects, either greenfield or in prepping older wells through enhanced oil recovery techniques.
The second major reason for this continuous hiring effort from the oil companies is talent shortage. Today, there are so many jobs, particularly in technical fields, filled by graying workers hired in the 1970s. Most of them will be reaching retirement age in a few years. While the oil and gas companies looking to rejuvenate its work force with young blood, your prospects of getting positions in this sector s remains strong.
Tuesday, November 25, 2008
Oil below $40 per barrel?
Deutsche Bank AG has said that Oil prices may fall as low as $40 a barrel by April as demand collapses and production costs eases. In a report published on Bloomberg, Deutsche have said:
“Cash production cost ‘floors’ for the oil price are a shrinking target because of lower costs and a stronger U.S. dollar…This implies a `V' shaped downside to $40 a barrel crude around April 2009.”
Oil has dropped 63 percent from a record $147.27 in July. As on yesterday, crude futures hovered around $54 a barrel mark. In a separate item reported in the Financial Times, top executives from national oil company of China have predicted about $40 a barrel, thereby putting quiet a few new oil-exploration projects at risk of cancellation.
Oil that cheap is a major concern for big oil-producing countries like Iran, Iraq, and Venezuela. Any cut in production by OPEC, the cartel of oil exporting countries, is not likely to be as effectual as it was once thought to be. OPEC’s previous announcement of output reduction of 1.5m barrels a day failed to revive the falling crude oil price. The group's biggest producer, Saudi Arabia, will “move cautiously” amid the increase in the supply of non-conventional oils such as ethanol in the U.S.
However, this development has another implication. Cheaper oil could also take out some steam out of the push for clean energy in the US – which is much costlier.
Monday, November 24, 2008
Busting some myths
There has been a fair amount of discussion about energy policies in the recent past, aided in no small part by the interest generated in the recently concluded U.S. presidential election. Some facts that were thrown about has been taken as received wisdom. We examine some of these here.
1. Oil companies are extracting extra “economic rents” for the high price of gasoline/petrol
There are many factors that resulted in the run up of gasoline price. About 70-75% of the price is that of crude and refining/distribution/service station charges. The government taxes comprises of 10-15% depending on regulatory regimes. At the end of the day, Oil and Gas companies earn about 5-10% as profit.
There are also several additional factors that impact the price at the pump- cost of exploration and development, cost of extraction (the cost of human services as part of this is another story- more on this in another post), refining cost (no new refineries have been commissioned in the US in the past 17 years). I also think that the cost of speculation was a big factor- note the rapid decline in price in the last two months as many margin call positions were liquidated in the oil futures markets.
2. Oil companies are not investing in alternative energies.
The U.S. oil and natural gas industry invested almost $100 billion between 2000 and 2005 in emerging energy technologies, including $12 billion in non-hydrocarbons and $42 billion in greenhouse gas emission mitigation technologies from 2000 to 2006. This is not mere green PR, but real investments.
There have also been some advances in less intrusive technologies for exploration and production. However, the industry has successfully developed breakthrough technologies like 4D seismic imaging and multi-directional drilling, which have helped reduce the industry’s environmental footprint dramatically. Today it is possible to develop nearly 80 square miles of area below the surface from a single two-acre site on the surface.
Thursday, November 20, 2008
SPE Salary Survey
Society of Petroleum Engineer (SPE) recently released its annual salary survey for the Oil & Gas sector. I must say that I was delighted to find the result of the survey which is very promising and reassuring especially in this period of economic gloom! At a time when global giants are tumbling, people are being laid off in the thousands, the report findings are in stark contrast to the global economic slowdown. You can download the complete results here.
This survey was SPE’s second effort. Last year a similar survey was carried out among SPE members. This time around, the scale of respondents was higher and so was the diversity in their demography. Unlike last year, more than half of the respondents are working in countries other than the United States. In total, there were respondents representing 125 nations, working in 116 different countries around the world including a sizable number from North Sea/North Atlantic and Middle East regions.
A quick overview on the findings of the survey –
The average annual increase in base pay is reported as 8.1% overall. The work region with the highest increase is Australia/New Zealand, at 10.6%, while Canada is lowest with 7.3%.
This is great in comparison to other sectors where growth in the mid/high level is much less and in many cases, almost stagnant.
The United States, Australia/New Zealand, and North Sea/North Atlantic have the highest average pay in the industry while Southeast Asia being distinctly the lowest paid.
The average age of respondents is consistent around the globe – around 39 to 45 years.
If you’re looking to join this sector, here’s proof positive of the amount of money you can make. If you’re already in the business, you can do a quick benchmark against professionals in other geographies, disciplines and experience brackets.
Thursday, November 13, 2008
Double trouble: deflationary oil prices & financial meltdown
Overlapping Crises
The current financial crisis has ballooned around the world economy and there are fears that this international recession could even trigger a global economic meltdown. Most economic analysts are predicting that it will get worse before it gets better. This is reflected in some of the recent downswings in stock markets worldwide as near term recessionary expectations are being priced in today. The channels of credit have dried up and businesses small and large have been plagued by a credit crunch.
The other key trend is in the sharp volatility of hydrocarbons prices. After a remarkable run up over the last two years, crude prices have plummeted over the past few months. We hit $58 for crude today; and will probably drop further as the global demand cycle weakens in the near term. While there are many factors driving the price of oil (demand- supply, speculation, political risk, etc), it is undeniable that there has been some demand destruction due to unsustainable high prices in the $150 range.
Effect on Projects
So how is this price deflation and the economic crisis at large going to effect the industry, and industry jobs in particular?
In the last few years, quite a few operators were able to leverage cheap credit and high commodity prices to finance large new exploration projects in some new areas. However with the squeeze in the credit markets, some of these projects are either being put on hold or delayed. Small cap companies are scaling back operations, seeking new partners or have become targets for acquisition. There are other companies are also restructuring their project plans to tide over the current period of economic uncertainty. Shell recently announced the delay of its oil sands project in Canada, Yemen has also delayed its gas production outlook. However, most large cap integrated oil companies are not cutting back as they did not factor in prices in the $140 range while making their investment decisions. This is also the case for most national oil companies.
In the long term, my sense is that the demand-supply equation will be unbalanced. The IEA predicted last week in its World Energy Outlook that by 2010 oil companies will have to commit to projects producing almost as 7m barrels a day – if the world is to avoid a supply crunch by the middle of the next decade. This is due to the steep rates of decline in existing fields to meet demand of growing economies like China and India. Further investments should stanch the natural rate of output decline of 9% down to 6.7%. As a result they have predicted a price range greater than $100 by 2015.
Outlook
So the question is how will the credit crunch and lower oil prices affect the labor market in the Oil and Gas industry? Will it stall the recruitment and talent acquisition process? Are we going to see a repeat of the layoffs of the 1980s?
It’s early to say right now; we may have more volatility coming down the pike. But over the medium term once key economies right themselves, demand should increase. China has taken a good step in that direction this week. Only time will tell, but I feel pretty optimistic.
What do you think?
Friday, November 7, 2008
Life in Kazakhstan
Kazakhstan is among the most important geographies for the upstream sector. The country currently has the 11th largest proven reserves of both oil and natural gas. Estimate indicates that there is over 2.7 billion tons of petroleum scattered in about 160 deposits.
The 9th largest country in the world is bordered by Russia, Kyrgyzstan, Turkmenistan, Uzbekistan, China and a significant part of the Caspian Sea. It is widely believed that the Caspian shore is only a small part of a much larger deposit and that 3.5 billion tons of oil and 2.5 trillion cubic meters of gas could be found in that area.
However, I do not intended to give you the facts and figures of Kazakhstan’s natural resource nor an account of its diversity in terrain – flatlands, steppes, taigas, rock-canyons, hills, deltas, mountains, snow-capped mountains, and deserts. What I would like to dwell upon in this post is the country and its people which energy professionals might find useful in case they take up a project in the country.
 Let me begin by saying that Kazakhstan is not at all like the way it was stereotyped in the movie Borat! The cities are clean, complete with ample civil amenities. There are many wide boulevards, lots of trees, and the roads are generally well kept. Though there are no published routes, it’s easy to find your way around. There are city buses, trolleys, and trams making it easy to move around. However, things are not as well kept as you progress farther from the mountains towards the outskirts. It would be a tad harsh to expect the same level of convenience in all parts of a country where the population density is less than 6 people per square kilometer.
History
Kazakhstan was part of the Russian Empire. Kazakhstan declared itself an independent country on December 16, 1991. Nursultan Nazarbayev – its communist-era leader, became the country's new president. While the country's economic outlook is improving, President Nazarbayev maintains strict control over the country's politics.
People and Religion
Kazakhstan has historically hosted a wide variety of ethnic groups with varying religions. Tolerance to other societies has become a part of the Kazakh culture. One of the major reasons of ethnic and cultural diversity is because of mass deportations of many ethnic groups to the country during Stalin's rule. Kazakhs are the largest group, followed by Russians. Kazakhstan allows freedom of religion, and many different beliefs are represented in the country. Islam is the primary religion, followed by Orthodox Christianity. The official language is Kazakh, though Russian is still commonly used for everyday communication.
Food Habits

One of the major concerns of people going abroad to stay for a longer period of time is the eating habits of the host country. Generally, diet consist of lots of vegetable and livestock meat cooked in many ways and served with traditional bread. People belonging to the Western countries might be surprised by the amount of fried food here! A Peace Corp volunteer writes in her blog that “Every soup has a little oil floating on the top”
Most of us like our tea, coffee or even a cup of hot chocolate in cold winters while during summers, we resort to juice, lemonade or even iced tea. But Kazaks drink lots of tea throughout the year. Tea breaks are common, and along with the tea breaks there is a variety of cookies and candy. Another peculiarity is that there aren’t any designated breakfast, lunch and dinner foods and it is common to have the same soup for dinner and then breakfast the following morning.
Culture
Traditional moral values of Kazakhs are respect of the elders and hospitality to strangers. This makes it easy for foreigners to ask around and find out places. An average Kazak goes out of his way to help a tourist with language barrier. The country has an impressive 99.5% adult literacy rate, thanks to a well-structured education system comprising of many reputed universities, academies, and institutes, conservatories, higher schools and higher colleges.
Because livestock was central to the Kazakhs' traditional lifestyle, most of their current practices and customs relate in some way to livestock. For example, it is considered as good manners for an average Kazak to ask first about the health of a man's livestock when greeting him and later inquire about the human aspects of his life.
The country’s largest city – Almaty is considered to be the musical capital of Central Asia. Well-known artists such as Deep Purple, Tokyo Hotel, Atomic Kitten, Dima Bilan, Loon, Craig David, The Black Eyed Peas, Eros, Ace of Base and others have recently toured the country.
Kazakhstan is a very pleasant country with picturesque landscape almost everywhere. Once your Russian is good enough, it is almost like working in a picnic spot.
The 9th largest country in the world is bordered by Russia, Kyrgyzstan, Turkmenistan, Uzbekistan, China and a significant part of the Caspian Sea. It is widely believed that the Caspian shore is only a small part of a much larger deposit and that 3.5 billion tons of oil and 2.5 trillion cubic meters of gas could be found in that area.
However, I do not intended to give you the facts and figures of Kazakhstan’s natural resource nor an account of its diversity in terrain – flatlands, steppes, taigas, rock-canyons, hills, deltas, mountains, snow-capped mountains, and deserts. What I would like to dwell upon in this post is the country and its people which energy professionals might find useful in case they take up a project in the country.
 Let me begin by saying that Kazakhstan is not at all like the way it was stereotyped in the movie Borat! The cities are clean, complete with ample civil amenities. There are many wide boulevards, lots of trees, and the roads are generally well kept. Though there are no published routes, it’s easy to find your way around. There are city buses, trolleys, and trams making it easy to move around. However, things are not as well kept as you progress farther from the mountains towards the outskirts. It would be a tad harsh to expect the same level of convenience in all parts of a country where the population density is less than 6 people per square kilometer.
History
Kazakhstan was part of the Russian Empire. Kazakhstan declared itself an independent country on December 16, 1991. Nursultan Nazarbayev – its communist-era leader, became the country's new president. While the country's economic outlook is improving, President Nazarbayev maintains strict control over the country's politics.
People and Religion
Kazakhstan has historically hosted a wide variety of ethnic groups with varying religions. Tolerance to other societies has become a part of the Kazakh culture. One of the major reasons of ethnic and cultural diversity is because of mass deportations of many ethnic groups to the country during Stalin's rule. Kazakhs are the largest group, followed by Russians. Kazakhstan allows freedom of religion, and many different beliefs are represented in the country. Islam is the primary religion, followed by Orthodox Christianity. The official language is Kazakh, though Russian is still commonly used for everyday communication.
Food Habits

One of the major concerns of people going abroad to stay for a longer period of time is the eating habits of the host country. Generally, diet consist of lots of vegetable and livestock meat cooked in many ways and served with traditional bread. People belonging to the Western countries might be surprised by the amount of fried food here! A Peace Corp volunteer writes in her blog that “Every soup has a little oil floating on the top”
Most of us like our tea, coffee or even a cup of hot chocolate in cold winters while during summers, we resort to juice, lemonade or even iced tea. But Kazaks drink lots of tea throughout the year. Tea breaks are common, and along with the tea breaks there is a variety of cookies and candy. Another peculiarity is that there aren’t any designated breakfast, lunch and dinner foods and it is common to have the same soup for dinner and then breakfast the following morning.
Culture
Traditional moral values of Kazakhs are respect of the elders and hospitality to strangers. This makes it easy for foreigners to ask around and find out places. An average Kazak goes out of his way to help a tourist with language barrier. The country has an impressive 99.5% adult literacy rate, thanks to a well-structured education system comprising of many reputed universities, academies, and institutes, conservatories, higher schools and higher colleges.

Because livestock was central to the Kazakhs' traditional lifestyle, most of their current practices and customs relate in some way to livestock. For example, it is considered as good manners for an average Kazak to ask first about the health of a man's livestock when greeting him and later inquire about the human aspects of his life.
The country’s largest city – Almaty is considered to be the musical capital of Central Asia. Well-known artists such as Deep Purple, Tokyo Hotel, Atomic Kitten, Dima Bilan, Loon, Craig David, The Black Eyed Peas, Eros, Ace of Base and others have recently toured the country.
Kazakhstan is a very pleasant country with picturesque landscape almost everywhere. Once your Russian is good enough, it is almost like working in a picnic spot.
Tuesday, October 21, 2008
Oil & Gas Careers: Things to consider
The Dallas Morning News has suggested in one of its article by Elizabeth Souder that “This is a great time to look for a job in the oil industry.” Her report is largely based the oil prices and an aging industry workforce – something we have been following & acting upon for some time. With the rise in oil prices over the last two years (and notwithstanding the recent gyrations the past few weeks), there is increased enrollment in petroleum engineering and geology programs worldwide.
However, it is advisable not to base one’s career decision based on the commodity market. Before you decide to join the petroleum industry, here are a few things to consider.
Basic Aptitude
Strengths in science and mathematics are the backbone of petroleum engineering and geology careers. You will be doing a fair bit of analysis & modeling in your future roles. If you don’t have the the aptitude in the basic physical sciences you may want to consider other options.
Global Mobility
This industry is one of the most global in nature. Hydrocarbons are found in more than 80 countries, but its likely that in the next two decades extractable oil may be developed in more inhospitable climes. You can look forward to a fair bit of travelling in the Exploration & Production aspect of this sector, particularly if you join a oil services organization. This may strike a chord with you if you’re adventurous in nature, If frequent traveling is not your cup of tea you may want to evaluate other aspects of this sector; particularly in refining or marketing of hydrocarbons.
Cyclicality
The 90s saw a decline in prices which depressed the number and types of jobs in the sector. The past few years on the other hand has been characterized by a steep price rise as well as volatility. During boom times it does seem that the tipping point is far away, however know that Oil & Gas, much like other commodities, is a fairly cyclical industry. A future slowdown in the industry will effect the job market too. However the skills that you will pick up in this industry, including the managing complex engineering projects, data intensive modeling or opening new markets for hydrocarbons will stand you in good stead in other industries.
In summary, the industry is growing and is exciting. However you may want to take a longer term view as you plan on venturing into this field.
Subscribe to:
Posts (Atom)